Last checked 2 November 2026
When you need one
Rule 138 of the CGST Rules requires an e-way bill before goods move when the consignment value is more than ₹50,000. That applies to a sale, a movement for any other reason (job work, branch transfer, return), and purchases from an unregistered supplier.
- Consignment value is the invoice value plus GST and cess, leaving out exempt goods on the same bill.
- Several States set a higher limit for movement within the State. Check your State’s notification before relying on ₹50,000 for local deliveries.
- Always needed, whatever the value: inter-State movement of goods for job work, and inter-State movement of handicraft goods by a person exempt from registration.
- Not needed for goods carried by a non-motorised conveyance like a handcart, goods listed in the Rule 138 annexure (such as household LPG and used personal effects), and some other notified cases.
Part A and Part B
| Part | What it holds | Who fills it |
|---|---|---|
| Part A | GSTIN of supplier and recipient, place of delivery, document number and date, value, HSN, reason for transport, transporter | Consignor, consignee or the transporter on their behalf |
| Part B | Vehicle number (road) or transport document number (rail, air, ship) | Whoever moves the goods |
Part B can be skipped when goods move up to 50 km within the same State between your place of business and the transporter’s place (or from the transporter to the recipient). The e-way bill becomes valid for movement only once Part B is filled. A transporter carrying several consignments in one vehicle makes a consolidated e-way bill.
How long it is valid
| Vehicle | Validity |
|---|---|
| Normal cargo | 1 day for up to 200 km, plus 1 day for every further 200 km or part of it |
| Over-dimensional cargo | 1 day for up to 20 km, plus 1 day for every further 20 km or part of it |
Each day runs until midnight, and the first day ends at midnight of the day after generation. Example: an e-way bill made at 10:00 on 5 November for a 450 km trip gets 3 days (200 + 200 + 50 km). Day one ends at midnight at the end of 6 November, so the bill is valid until 23:59 on 8 November. The portal prints the exact “valid until” time on every e-way bill.
Extend, cancel, reject
- Extend: the current transporter can extend validity from 8 hours before expiry until 8 hours after it, stating the reason and the remaining distance.
- 360-day cap: since 1 January 2025 an e-way bill cannot be extended beyond 360 days from the date it was first generated.
- Cancel: within 24 hours of generation, if it has not been verified in transit.
- Reject: the recipient can reject an e-way bill made against its GSTIN within 72 hours, or before delivery if earlier.
The 2025 changes
A GSTN advisory of 17 December 2024 announced changes to the e-way bill and e-invoice systems:
- 180-day rule: from 1 January 2025 an e-way bill can be generated only for documents dated within 180 days. An invoice older than that cannot be used.
- 360-day extension cap (above).
- Multi-factor authentication on the e-way bill and e-invoice portals: mandatory from 1 January 2025 for turnover above ₹20 crore, from 1 February 2025 above ₹5 crore, and from 1 April 2025 for everyone. Keep the mobile number on your GSTIN current.
Penalties
Moving goods without a required e-way bill can lead to detention of the goods and vehicle under section 129 of the CGST Act, released on payment of a penalty of 200% of the tax payable when the owner comes forward. Section 122 also provides a penalty of ₹10,000 or the tax evaded, whichever is higher. Small errors such as a single-digit mistake in the vehicle number are usually dealt with under a lighter penalty, but the bill should be corrected.
Before the vehicle leaves: a checklist
- Is the consignment value (with tax) above ₹50,000, or above your State’s limit for local movement?
- Is the document date within the last 180 days?
- Is the distance right? The portal checks it against the PIN codes.
- Is Part B filled with the right vehicle number, unless the 50 km exception applies?
- Does the driver have the invoice or challan and the e-way bill number (a printout or the number on the phone)?
How billinginfo helps
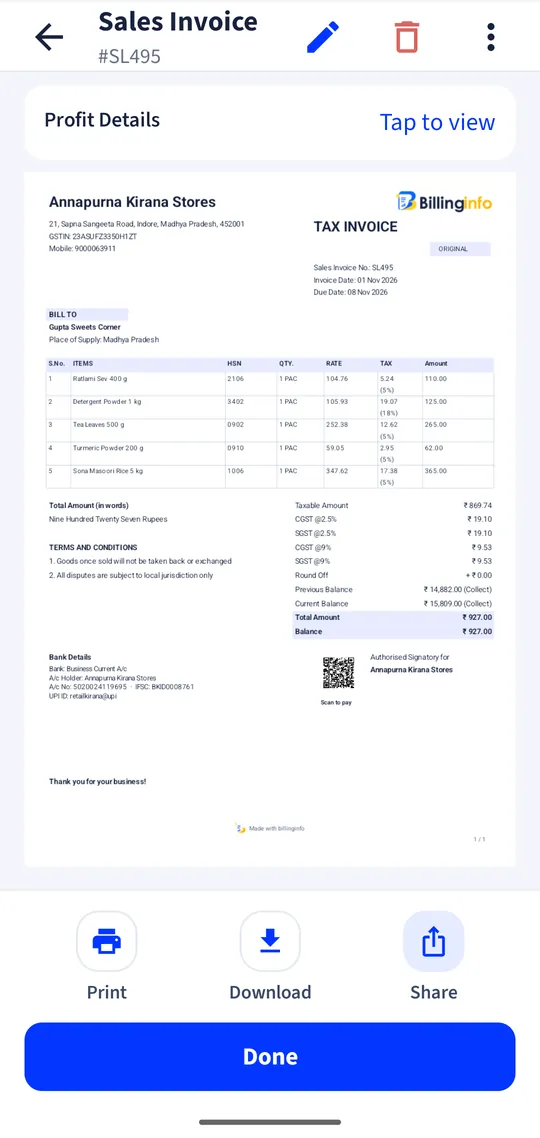
On the Plus, Pro and Max plans billinginfo generates the e-way bill straight from a sales invoice, delivery challan or return, using the GSTINs, HSN codes and values already on the bill. You can add or update Part B, extend validity, cancel, and make consolidated e-way bills, from the phone or the web app. See e-way bill software.