Last checked 2 November 2026
The one rule to remember
Compare the location of the supplier (the State of your GSTIN) with the place of supply:
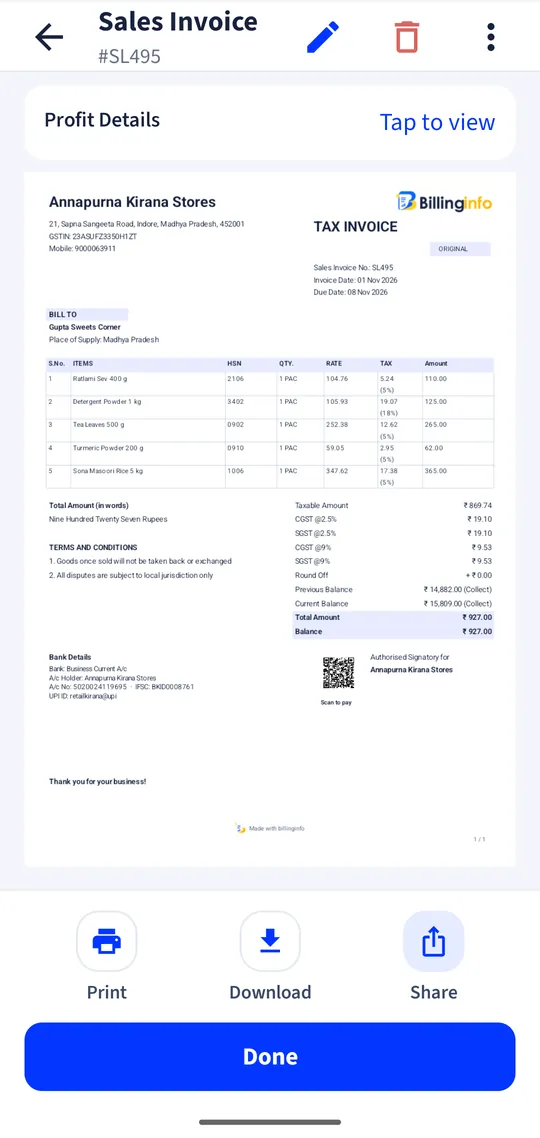
- Same State or Union Territory: intra-State supply. Charge CGST + SGST (or CGST + UTGST), half each. Section 8 of the IGST Act.
- Different States: inter-State supply. Charge IGST at the full rate. Section 7 of the IGST Act.
- Exports, imports and supplies to SEZ units or developers are always treated as inter-State, so they carry IGST (or are zero-rated).
The rate stays the same; only the split changes. 18% is CGST 9% + SGST 9% or IGST 18%. The hard part is finding the place of supply, which sections 10 and 12 of the IGST Act define.
Goods (section 10)
| Case | Place of supply | Example |
|---|---|---|
| Goods are moved to the buyer | Where the movement ends | A Jaipur trader sends tiles to a buyer in Ahmedabad: Gujarat, so IGST |
| Bill-to one party, ship-to another, on the instructions of a third person | The principal place of business of the person who gave the instruction (the bill-to party) | A Delhi firm buys from a Haryana mill and asks it to ship to the Delhi firm’s customer in Haryana: Delhi, so IGST |
| No movement (sold where it lies) | Where the goods are when delivered | A car sold off the showroom floor: the showroom’s State |
| Goods assembled or installed at a site | Where they are installed | A lift installed in a building in Goa: Goa |
| Goods supplied on a train, bus or ship | Where the goods were taken on board | Snacks loaded at Mumbai on a train to Delhi: Maharashtra |
A walk-in customer at your counter is always intra-State, even if the customer lives in another State: the goods are delivered at your shop.
Services (section 12)
When both you and your customer are in India:
| Service | Place of supply |
|---|---|
| General rule, registered customer | The customer’s registered location (State of the customer’s GSTIN) |
| General rule, unregistered customer | The customer’s address on record; if none, your location |
| Services related to immovable property (construction, renting, hotel stay, architecture) | Where the property is located |
| Restaurant, catering, beauty, fitness, health services | Where the service is actually performed |
| Training and performance appraisal | Registered customer’s location; otherwise where performed |
| Admission to an event or venue | Where the event or venue is |
| Transport of goods (including courier) | Registered customer’s location; otherwise where the goods are handed over for transport |
| Passenger transport | Registered customer’s location; otherwise where the passenger embarks |
Example: a Kolkata hotel bills a Bengaluru company with a Karnataka GSTIN for a room. The property is in West Bengal, so the place of supply is West Bengal and the hotel charges CGST + SGST, which the company usually cannot claim in Karnataka. Travel agents and event planners meet this rule often.
What to print on the invoice
Rule 46 requires the place of supply with the State name on inter-State invoices. Writing it on every invoice, with the State code, is the safest habit: “Place of supply: 24-Gujarat”. For unregistered buyers of ₹50,000 or more you also need the buyer’s State name and code. GSTR-1 reports B2C inter-State sales by place of supply, so a missing State on B2C bills turns into a reporting problem later.
Charged the wrong tax?
If you charged CGST + SGST where IGST was due (or the other way round), you cannot simply shift the amount. Section 77 of the CGST Act and section 19 of the IGST Act say: pay the correct tax, then claim a refund of the tax wrongly paid. No interest is charged on the correct tax if you pay it within the time allowed. In practice:
- Issue a credit note cancelling the wrong tax and a fresh invoice with the right tax, or amend the invoice in GSTR-1.
- Pay the correct tax in GSTR-3B.
- Claim a refund of the wrongly paid tax on the portal (Form RFD-01).
Avoiding the error is far easier. Most mistakes come from a missing or wrong State on the party.
Quick checks before you save a bill
- Does the buyer’s GSTIN start with your State code? If yes, CGST + SGST; if not, IGST (for goods moved to the buyer).
- Is the ship-to address in a different State from the bill-to? Read the bill-to ship-to row above.
- Is it a hotel, event or property service? The property or venue decides, not the buyer.
- Is the buyer an SEZ unit? IGST or zero-rated under LUT, never CGST + SGST.
How billinginfo helps
billinginfo takes the place of supply from the party’s State (or the first two digits of its GSTIN) and splits tax into CGST + SGST or IGST on its own. You can change the place of supply on a bill when goods are shipped elsewhere, and the bill prints the State name and code. The GSTR-1 report then groups B2C sales by State as the return needs.