Last checked 2 November 2026
Due dates
| You file | Period | Due date |
|---|---|---|
| Monthly | Each month | 11th of the next month |
| Quarterly (QRMP scheme, turnover up to ₹5 crore) | Each quarter | 13th of the month after the quarter |
| IFF (optional, QRMP only) | First and second month of the quarter | 13th of the next month, B2B invoices up to ₹50 lakh a month |
GSTR-1 must be filed before GSTR-3B for the same period. QRMP taxpayers use the Invoice Furnishing Facility (IFF) so their business buyers can claim credit every month instead of waiting for the quarter.
What goes where
| Table | What you report |
|---|---|
| 4 – B2B | Invoices to registered buyers, one by one, with GSTIN, number, date, value, rate and place of supply. Also reverse charge supplies |
| 5 – B2CL | Inter-State invoices to unregistered buyers above ₹1 lakh, one by one (the limit was ₹2.5 lakh until July 2024) |
| 6 – Exports | Exports and supplies to SEZ, with shipping bill details |
| 7 – B2CS | All other sales to consumers, totalled by State and rate |
| 8 – Nil, exempt, non-GST | Totals of exempt and nil-rated supplies |
| 9 – Amendments, CDNR, CDNUR | Changes to earlier invoices; credit and debit notes to registered and unregistered buyers |
| 11 – Advances | Advances received and adjusted |
| 12 – HSN summary | Sales by HSN code with quantity, value and tax, split into B2B and B2C |
| 13 – Documents issued | Ranges of invoice, credit note and challan numbers, with cancelled ones |
| 14, 15 – E-commerce | Supplies made through e-commerce operators |
A worked example
Annapurna Stores in Pune (State 27) makes these sales in October:
- Three bills to registered grocers in Pune: ₹1,20,000 taxable at 5%. Goes into B2B, one row per invoice.
- One bill of ₹1,40,000 to an unregistered hotel in Goa: inter-State, unregistered, above ₹1 lakh. Goes into B2CL.
- Counter sales of ₹6,80,000 to walk-in customers at 5% and 18%. Goes into B2CS: one line per rate for State 27.
- One sales return credit note of ₹8,000 to a registered grocer. Goes into CDNR.
- Table 12 adds up everything by HSN; Table 13 lists invoice numbers 1 to 412 with 3 cancelled.
Corrections: amendments and GSTR-1A
Mistakes found after filing are fixed in a later GSTR-1 through the amendment tables. Since July 2024 there is also GSTR-1A, an optional form to add or correct details of the same period after filing GSTR-1 and before filing GSTR-3B. From the July 2025 tax period the outward tax that GSTR-3B fills in from GSTR-1, IFF and GSTR-1A cannot be edited in GSTR-3B, so corrections must be made through GSTR-1A or the amendment tables.
Late fee and the three-year bar
Late filing costs a fee for each day of delay, capped by your turnover (Notification 20/2021-Central Tax):
| Return and turnover | Late fee per day (CGST + SGST) | Maximum per return |
|---|---|---|
| Nil return (no sales, no tax) | ₹20 (₹10 + ₹10) | ₹500 |
| Aggregate turnover up to ₹1.5 crore | ₹50 (₹25 + ₹25) | ₹2,000 |
| ₹1.5 crore to ₹5 crore | ₹50 | ₹5,000 |
| Above ₹5 crore | ₹50 | ₹10,000 |
Example: a business with ₹90 lakh turnover files a monthly GSTR-1 for October on 21 November instead of 11 November: 10 days × ₹50 = ₹500 (₹250 CGST + ₹250 SGST). Use the late fee calculator for your dates. From the July 2025 tax period the portal does not accept GSTR-1 more than three years after its due date.
Common mistakes
- Wrong buyer GSTIN: the buyer does not get the credit, and someone else might.
- Putting an inter-State B2C sale under your own State in B2CS.
- HSN summary that does not match the invoices, or HSN codes with too few digits.
- Forgetting credit notes, so output tax is overstated.
- Skipping Table 13. It is now validated more closely and helps prove your invoice series.
Monthly or quarterly: which suits you?
Monthly filing means more returns but faster credit for your buyers and earlier sight of mistakes. QRMP means four GSTR-1s a year, but tax is still paid every month through PMT-06. If most of your buyers are registered businesses, they will prefer you to use IFF so their credit is not delayed. A shop that sells mostly to consumers loses little by filing quarterly.
How billinginfo helps
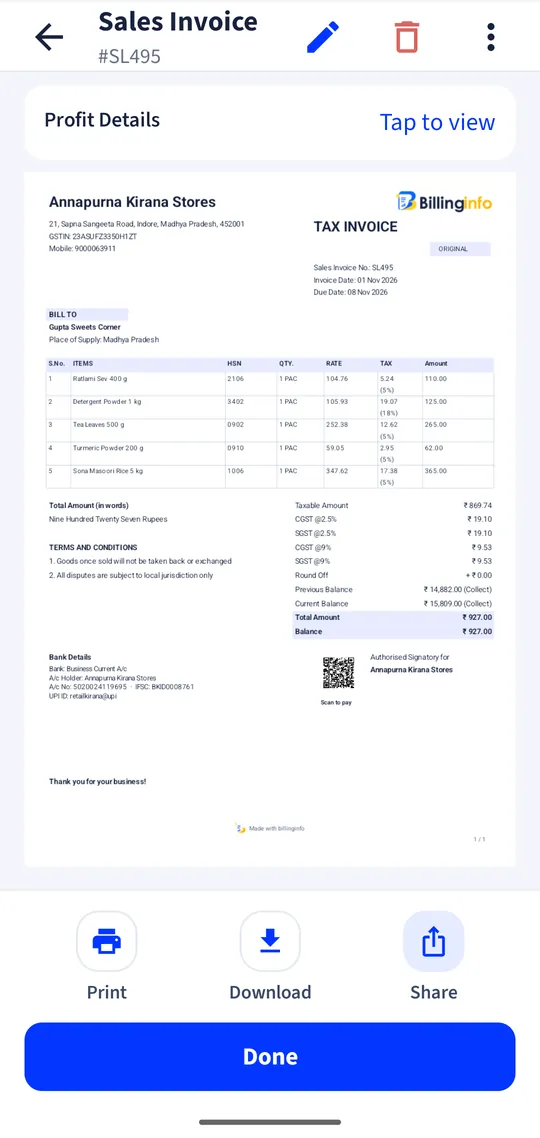
billinginfo builds the GSTR-1 report straight from your bills: B2B, B2CL, B2CS, credit and debit notes and the HSN summary, ready to export to Excel for you or your accountant to file on the GST portal. billinginfo does not file GSTR-1 for you. See GST reports.