Ganesh TradersShop 14, Market Yard, GultekdiPune, Maharashtra 411037GSTIN: 27AAMFG1503P1Z5Phone 98220 41503accounts@ganeshtraders.example
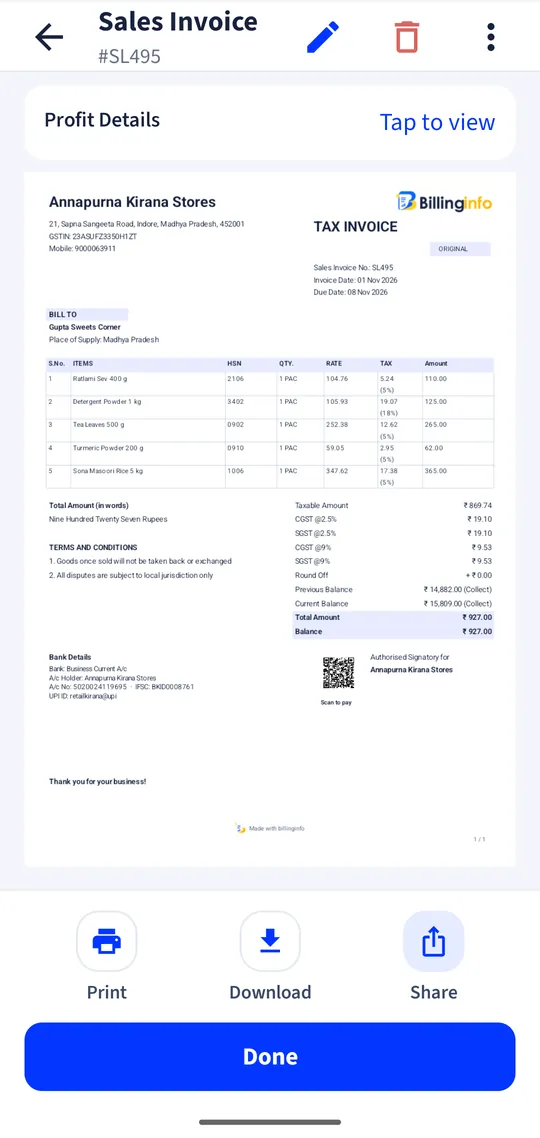
TAX INVOICEOriginal for recipient
Bill toAnnapurna Kirana Stores7, Karve Road, KothrudPune, Maharashtra 411038GSTIN: 27AFWPA6624L1ZYState code 27
| # | Item | HSN | Qty | Rate | Disc | GST | Amount |
|---|---|---|---|---|---|---|---|
| 1 | Toor Dal, 25 kg bagPre-packed and labelled | 0713 | 4 bag | 3,150.00 | 5% | 12,600.00 | |
| 2 | Sunflower Oil, 15 L tin | 1512 | 3 tin | 2,040.00 | 5% | 6,120.00 | |
| 3 | Toothpaste 150 g | 3306 | 48 pcs | 92.00 | 5% | 5% | 4,195.20 |
| 4 | Detergent Powder 1 kg | 3402 | 40 pac | 108.00 | 18% | 4,320.00 |
Amount in words
Rupees Twenty Nine Thousand One Hundred Fifty Nine Only
Bank details
Ganesh Traders, Current account 50200041503 · IFSC HDFC0000123 · UPI ganeshtraders@hdfcbank
Terms
Payment within 15 days. Goods once sold are taken back only if damaged in transit, reported within 48 hours.
| Taxable value | ₹27,235.20 |
|---|---|
| CGST @2.5% on 22,915.20 | ₹572.88 |
| SGST @2.5% on 22,915.20 | ₹572.88 |
| CGST @9% on 4,320.00 | ₹388.80 |
| SGST @9% on 4,320.00 | ₹388.80 |
| Round off | +0.44 |
| Total | ₹29,159.00 |
For Ganesh TradersAuthorised signatory
Sample with a fictitious business · made with billinginfo